Crypto
Bitcoin ETFs Whipsaw: $1.08 Billion In, Then $773 Million Out

Spot funds still finished the week with a modest gain, but the reversal exposed how tactical institutional demand has become.
US spot Bitcoin exchange-traded funds spent the week of October 19 doing something they have done repeatedly this year: attract a wave of money and then hand a large part of it back. By Friday’s close the funds had recorded about $301 million of net inflows for the week, according to figures compiled from SoSoValue and Farside Investors. That snapped a two-week streak of withdrawals. The path to that number matters more than the total.
A strong start
Monday, October 19, brought roughly $526.7 million of inflows. Tuesday was quiet, with about $23 million. Wednesday, October 21, delivered another $524.8 million; some trackers put it at $528.4 million, a gap that reflects how and when each provider tallies issuer reports. Across those three sessions the funds took in about $1.07 to $1.08 billion.
BlackRock’s IBIT led on Wednesday with about $235 million, followed by Fidelity’s FBTC at roughly $213 million, with smaller amounts into Grayscale’s GBTC, Bitwise, Ark and Franklin Templeton. IBIT’s cumulative net inflow since launch stands at about $66.5 billion, the largest of any US Bitcoin fund. Monday’s mix was unusual: IBIT alone took in about $665 million while FBTC and GBTC saw outflows of roughly $84 million and $55 million. That day was flagged as showing the widest gap between Bitcoin and Ether fund flows since November 11, 2025.
The reversal
Then the mood flipped. On Thursday, October 22, the funds lost $635.6 million, the largest single-day withdrawal since June 25. Friday added a further outflow of about $138 million. In two sessions roughly $773 million left, erasing most of the week’s early gains. The Bitcoin price had slid below $82,000 on Thursday, and the outflows accompanied the wider risk-off turn described in the first story.
The monthly numbers show how choppy October has been. One tracker had October flows at negative $539.8 million through October 14, after five days of inflows and five of outflows, with the month’s worst day, negative $487.1 million, on October 7. Strong buying the following week pushed the month back into positive territory by October 21, with one analyst reporting about $463 million month-to-date. Thursday’s outflow dragged the figure to roughly negative $175 million, and adding Friday’s withdrawal would take it to somewhere near negative $310 million. Exact totals differ by provider, so treat them as approximate.
The year so far
The monthly pattern for 2026 is lumpy. According to TFTC’s tally, flows were positive in March (about $1.3 billion) and April (about $2.0 billion), sharply negative in May (about $2.4 billion out) and June (about $4.5 billion out), nearly flat in July at about $172 million in, and strong in August ($3.5 billion) and September ($2.6 billion). Year-to-date net inflows were only about $1.39 billion as of October 21, a modest figure for an industry whose products now hold more than $100 billion in assets. Since their January 2024 launch the funds have collected more than $57 billion in combined net inflows, per The Block’s tracker.
Those numbers describe an investor base that behaves tactically. Money tends to arrive when Bitcoin is rising and leave when it stalls, which is different from the steady long-term accumulation that boosters described when the products launched. It also means ETF flows are often a symptom of price moves rather than a cause, although large outflow days can add selling pressure in thin markets.
Beyond Bitcoin
Other crypto funds had a softer time. Spot Ether ETFs recorded about $110.6 million of withdrawals on October 22 and roughly $320.1 million of net outflows across October 12 to 16, so Ethereum products have been losing money for weeks. XRP funds attracted just $3.55 million on October 22, mostly into Franklin Templeton’s XRPZ. On the stronger Wednesday, Bitcoin, Ether, Solana and XRP funds together drew about $541 million, which shows that when risk appetite improves the altcoin funds participate, though only at the margins.
One newer product deserves a mention. Morgan Stanley’s Bitcoin ETF, launched in April, has recorded just one day of net outflows so far, according to The Block. It is small next to IBIT and Fidelity’s fund, but it reflects how traditional wealth platforms have moved from skepticism to offering their own products.
Why it matters
The live debate is about conviction. Optimists point out that inflows came back within days of every drawdown this year and that more than $100 billion in assets shows the funds are now embedded in portfolios. Skeptics note that May and June together pulled out nearly $7 billion, and that October is again showing strong buying into rallies and fast exits when conditions tighten.
Traders will watch whether ETF demand returns while Bitcoin holds the $80,000 to $81,000 area, a test one analyst described to The Block. If flows stabilize there, the outflows will look like noise. If they persist alongside falling prices, the market may need to find buyers elsewhere. As always, daily flow data is noisy, subject to revision and a poor guide to the next move on its own.
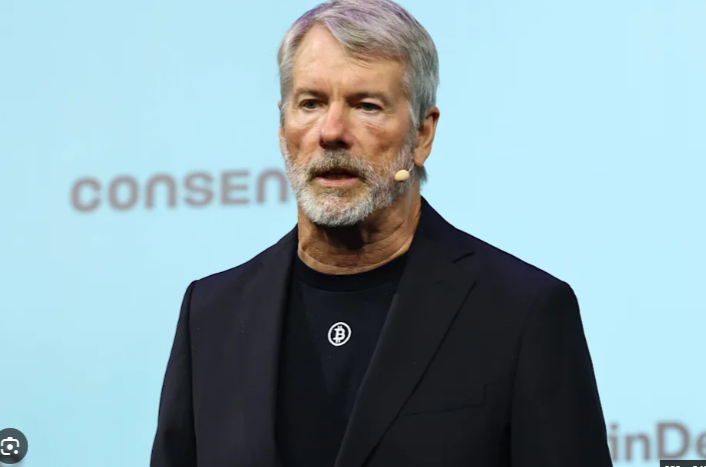
Michael Saylor is the best-known corporate Bitcoin evangelist. Born on February 4, 1965, and educated at MIT, he co-founded the business-intelligence software company MicroStrategy, now called Strategy, and serves as its executive chairman. He lives in Miami, and Forbes lists his source of wealth as cryptocurrency. Unlike the other people here, his story has two layers: a personal bet and a corporate one, which are related but not the same.
The personal bet
In 2020, Saylor disclosed that he had personally bought 17,732 Bitcoin for about $175 million, an average of roughly $9,900 per coin, according to Forbes and other profiles. At today’s price near $80,000 that holding is worth about $1.4 billion, roughly eight times the cost. On August 3, 2026, he said he has never sold any of his personal Bitcoin, a claim that profiles repeat but that rests on his own statement.
The corporate bet
The larger story is Strategy. In 2020 the company began using its cash and later borrowed and raised funds to buy Bitcoin. Forbes says Saylor helped trigger the institutional Bitcoin boom in December 2020, when Strategy’s Bitcoin ownership crossed $1 billion. Today, according to the company’s filings, Strategy holds about 848,500 coins bought for roughly $64 billion, an average near $75,400. At $80,000 a coin the holding is worth about $68 billion, so the unrealized gain is around $4 billion, far smaller than the $7 billion plus figures that circulated when Bitcoin traded higher. The company holds a little over 4 percent of all Bitcoin that will ever exist.
Saylor’s personal stake in the company is large. A 2025 profile said he owned about 9.9 percent of Strategy’s equity but controlled roughly 45 percent of the voting power, and earlier reports listed roughly 19.6 million to 20 million Class B shares. Those percentages may have changed, since the company has issued a great deal of stock.
A net worth that swings with the market
Because Strategy’s share price is tied to Bitcoin, Saylor’s wealth is volatile. Forbes estimated his net worth at about $7.37 billion in September 2025, about $4.7 billion in early February 2026, and roughly $3.0 to $3.2 billion in late June 2026, before returning to about $4.8 billion this autumn. The company’s structure adds leverage. One June analysis, citing Morningstar, counted about $6.7 billion of convertible debt and $15.5 billion of preferred obligations against the Bitcoin holdings, which makes the equity behave like a leveraged bet on Bitcoin.
The strain behind the success
This year has shown the costs. Strategy has spent heavily to support its STRC preferred stock, as described in the sixth story of the roundup, and it indicated in the first quarter that it might sell small amounts of Bitcoin to cover dividends. Forbes reports it then sold 1,638 bitcoin at about $63,957, below its roughly $75,400 average cost, to pay preferred dividends and fund STRC buybacks. CryptoQuant analysts put its realized losses from Bitcoin sales in 2026 above $102 million. Saylor has said none of his personal coins were sold.
The company also holds a USD Reserve of about $4.83 billion intended to cover dividends and interest, plus separate cash, but that cushion has to be defended against rising obligations. Strategy’s quarterly report says it has used convertible notes, senior secured notes and a loan backed by Bitcoin, and may borrow more.
The ambition and the pace
Some coverage has said Strategy aims to reach one million Bitcoin by the end of 2026. With about 848,500 coins and recent weekly purchases in the low hundreds, that would require roughly 151,000 more coins in about ten weeks, so the target looks out of reach at the current pace. We did not find a recent company statement reaffirming it, so treat the goal as reported ambition, not a commitment.
What supporters and critics say
Supporters credit Saylor with changing how companies think about holding Bitcoin, creating a template other treasury companies followed and drawing institutional attention to the asset. They point out that his personal return is real and that the company’s coins are still above cost.
Critics focus on risk and circularity. The model depends on raising capital at favorable prices to buy more Bitcoin, which becomes difficult when prices fall, and selling Bitcoin below cost to meet obligations is the scenario they warned about. They also point to the exposure created for investors in the preferred stock and the company’s stock if Bitcoin stays weak.
Lessons
Saylor’s record shows what conviction plus scale can do and what leverage can cost. The personal holding is simple: a large early purchase held through volatility. The corporate strategy is more complicated, because it relies on financing, and financing adds ways to lose. For a reader considering crypto, the difference matters. Holding coins you bought with your own money is one risk. Borrowing to buy more is a different and much larger one.
It also shows that billionaire headlines are not stable. A net worth that falls by more than half over four months and then recovers is a poor guide to what anyone should do with their own savings.
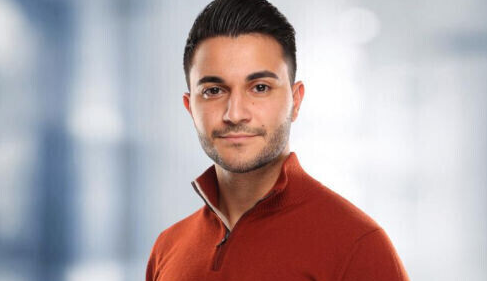
Dadvan Yousuf’s story contains both the most dramatic success claims and the most serious caveats in this series. According to Wikipedia he was born on April 9, 2000, in Zakho, in Iraq’s Kurdistan Region, holds Iraqi and Nauruan citizenship, and became known in Switzerland for early Bitcoin investments. Much of what is written about his wealth comes from self-promotion and secondary summaries, so this profile sticks to what coverage reports and flags what could not be verified.
The early bets
HackerNoon’s profile of crypto millionaires says Yousuf sold some of his toys at around age 11 in 2012 to buy Bitcoin, then bought Ether in 2016. He has been described as the youngest Swiss self-made millionaire. A people-profile site, citing the Swiss newspaper Blick, says his net worth was reported at 270 million Swiss francs in 2020, including 189 million in cryptocurrency, and that estimates based on market prices suggested his holdings could have exceeded 1.2 billion francs. Those figures come from a secondary source and from a period of rapid price change, so they should be treated as estimates rather than audited facts. He would have been about 20 at the time.
He moved to Zug, Switzerland’s crypto hub, in early 2021 to oversee development of his software and hold his tokens, and in November 2021 Forbes included him in one of its lists. His rise coincided with the 2020 and 2021 bull market, when many early holders saw their wealth multiply.
The Dohrnii Foundation and the DHN token
Yousuf later founded the Dohrnii Foundation, a crypto education project. According to its whitepaper, Dohrnii was designed as a blockchain-based financial education platform with a learn-to-earn model, in which users are rewarded with its DHN token for engaging with educational content, alongside a marketplace where services and products could be exchanged using the token. The DHN token was listed on a decentralized exchange in 2022 through a community initiative led by a decentralized autonomous organization.
Wikipedia reports that DHN reached a fully diluted market capitalization of $15 billion at its peak in 2025. That number needs context. A fully diluted valuation multiplies a token’s price by its total possible supply, including tokens that are locked, unissued or held by insiders. It is a headline figure, not the amount of money that could be withdrawn if holders tried to sell, and for thinly traded tokens the gap between the two can be enormous.
The regulatory problem
The other side of the story is the Swiss regulator. Coverage of his 2026 appointment, from outlets including Cointelegraph, Phemex and Crypto Economy, says Switzerland’s financial markets authority, FINMA, intervened over unauthorized activity linked to the Dohrnii Foundation. According to those reports, the foundation and its founder issued the DHN token without proper authorization, and FINMA ordered the foundation dissolved and liquidated, with related cease-and-desist orders. Other summaries describe the matter as unlicensed token sales tied to a defunct project he led. We did not review FINMA’s own documents, so readers who need exact dates, findings and the scope of the orders should consult the primary record.
This matters for how to read the success claims. A token’s market value is not the same as profit, and a project’s market value is not the same as its lawful operation. A regulator that orders a foundation liquidated is making a statement about the project, not about whether its founder’s earlier Bitcoin and Ether purchases were profitable.
Mount Everest and the public profile
Yousuf has also built a public profile through stunts. In 2024 he raised a Bitcoin flag on the summit of Mount Everest, which Wikipedia describes as making him the first Kurd and the first Iraqi to reach the top. He said the expedition was meant to draw attention to inequalities in access to financial education. Coverage of the climb is not evidence of wealth or of any crypto investment results, but it shows how personal branding is part of this story.
Nauru
In April 2026 the Pacific nation of Nauru named Yousuf its first international trade commissioner. President David Adeang said Yousuf brings a unique combination of entrepreneurial vision, an international network and deep understanding of digital asset markets. The role is diplomatic: he is to support cross-border engagement with virtual asset service providers, financial institutions and technology companies that might set up operations in Nauru. The appointment follows Nauru’s creation last year of the Command Ridge Virtual Asset Authority, a regulator that licenses crypto businesses and digital banks. Government messaging says it wants Nauru to become a hub for digital asset business, investment and jobs.
Several outlets noted that the choice would draw scrutiny because of the Swiss enforcement history, and they framed it as a test of how Nauru balances promotion with due diligence. Yousuf said he was honored to support the country’s long-term economic strategy.
What the numbers can and cannot tell you
Separating the claims into categories helps. The early Bitcoin and Ether purchases are plausible and consistent across sources, though the amounts and timing rest on his own account and press profiles. The net-worth figures come from a Swiss newspaper report as relayed by a profile site, and they relate to 2020. The $15 billion token valuation is a peak fully diluted figure, not realized gains. The Swiss regulatory action and the Nauru appointment are better documented, and they both belong in the picture.
Lessons
The first lesson is that early entry mattered here as elsewhere: he started young, when prices were low, and the 2020 and 2021 run-up multiplied the result. The second is that a founder’s wealth often comes from two different sources, investing and issuing, which carry very different risks. Gains on holdings are shaped by the market. Gains on a token you create depend on regulators, buyers and liquidity, and they can be reversed by a ruling.
The third is practical: when you read a success story, ask who is making the claim, what the figure measures and whether anyone independent has checked it. For Yousuf, the answers vary line by line.
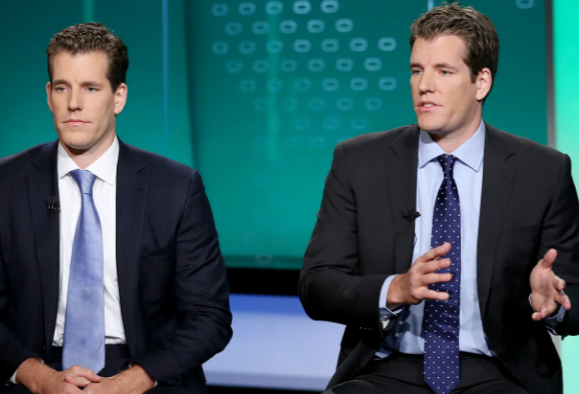
Two brothers share this profile because their financial lives are inseparable: they invested together, founded a company together and hold much of their wealth jointly. Cameron is president of the exchange Gemini, and Tyler is its chief executive.
The starting capital
Unlike the other people in this series, the Winklevoss twins began with serious money. They received a $65 million settlement from their long-running dispute with Facebook’s founder, and they put a portion of it into Bitcoin in the 2010s. Yahoo Finance reports that they invested about $11 million in Bitcoin and have held most of it since. When Bitcoin passed $11,000 in 2017, the pair were widely reported to have become the first Bitcoin billionaires. Their story therefore teaches something different from Finman’s or Koch’s: what happens when a large early position meets patience.
Building Gemini
In 2014 they founded Gemini, a cryptocurrency exchange aimed at institutions and wealthier investors, with an emphasis on regulation and security. Cameron serves as president and Tyler as CEO. The company went public as Gemini Space Station (Nasdaq: GEMI). Forbes described it in March 2026 as processing about $30 million a day in trades, and the company reported first-quarter 2026 revenue of $50.3 million, up 42 percent from a year earlier. With spot trading volumes subdued, Gemini has also launched a regulated event-trading market called Gemini Predictions.
How much do they hold?
Estimates differ, and they swing with prices. Yahoo Finance, writing last October, said the twins retained at least 70,000 Bitcoin, then worth about $8 billion, plus about 75 million Gemini shares worth roughly $1.5 billion, for a combined net worth of at least $9.5 billion. Forbes, in March 2026, put Cameron alone at about $2.8 billion and listed the brothers’ combined Bitcoin at an estimated 70,000 coins. A separate estimate has Cameron holding about 35,000 coins personally, which fits with half of the 70,000 combined. Other pages give combined net worth anywhere from $6 billion to $13 billion, reflecting different dates and methods.
Using the 70,000-coin figure, the Bitcoin alone is worth about $5.6 billion at today’s $80,000 price. If both numbers are right, an $11 million investment implies an average cost of a few hundred dollars per coin, a return of several hundred times before counting Gemini.
The drawdowns
The same exposure that made them rich also hurts in sell-offs. When Bitcoin crashed on October 10 last year, the brothers lost more than half a billion dollars from their combined net worth, according to Yahoo Finance. Gemini’s share price has fallen since that estimate, which implied about $20 a share, to around $5 in May. Forbes’s March figure for Cameron, about $2.8 billion, is well below the roughly $4.8 billion per brother that last October’s combined estimate would imply. The lesson is that billionaire status in crypto is a moving target: it can disappear from a headline as quickly as it appeared.
The $100 million statement
On May 14, 2026, the twins’ Winklevoss Capital Fund made a $100 million private investment in Gemini, paid in 1,258 Bitcoin, buying 7.1 million shares at $14 each when the stock traded around $5. The announcement came with the earnings report, and shares jumped more than 20 percent after hours. Tyler said the market had significantly undervalued the company. The twins had previously lent Gemini about $330 million. Separately, blockchain analytics firm Arkham spotted a $130 million Bitcoin transfer into Gemini in March, which some interpreted as a sale. That interpretation was not confirmed.
The deal can be read in two ways. Supporters see conviction, since the founders paid a large premium and used Bitcoin rather than cash. Skeptics note that insiders putting more money into a struggling listed company is also how a company with weak finances gets support. Both can be true.
What the twins’ story teaches
The first lesson is about capital. They could afford a sizable position and then wait, which most people cannot. The second is concentration. Their wealth rests on one asset and one company that depends on that asset’s popularity, so they feel every move in both. The third is that founders’ wealth and company health are linked: the loans and the May investment show how far a founder’s own money sometimes has to go to carry a public company through a weak market.
For an ordinary investor, the twins are a poor model. Few have a $65 million starting stake, access to institutional markets or the ability to absorb a half-billion-dollar swing. Their record is evidence that a large, early, patient position can compound enormously. It does not show that the same approach works from a smaller base or a later date.
-
 Elon Musk21 hours ago
The Boy from Pretoria Who Wanted to Save the World
-
 Elon Musk22 hours ago
Tesla: The Car Company That Refused to Stay a Car Company
-
 Elon Musk21 hours ago
Starlink: The Quiet Giant Inside SpaceX
-
 Elon Musk21 hours ago
From Zip2 to PayPal: How Musk Learned to Bet Everything
-
 Elon Musk21 hours ago
Neuralink: Elon Musk’s Attempt to Connect Brains and Computers
-
 Elon Musk21 hours ago
SpaceX and the Four Rockets That Almost Ended It All
-
 Crypto3 hours ago
Solana Tests the $100 Floor After Alpenglow Launches Into a Sell-the-News Reaction
-
 Elon Musk21 hours ago
The Boring Company: Can Elon Musk Dig Cities Out of Traffic